Global AI Stocks Plunge as $1.6 Trillion Is Wiped Out and CoreWeave Debt Yields Top 16%, Fueling Bubble Fears


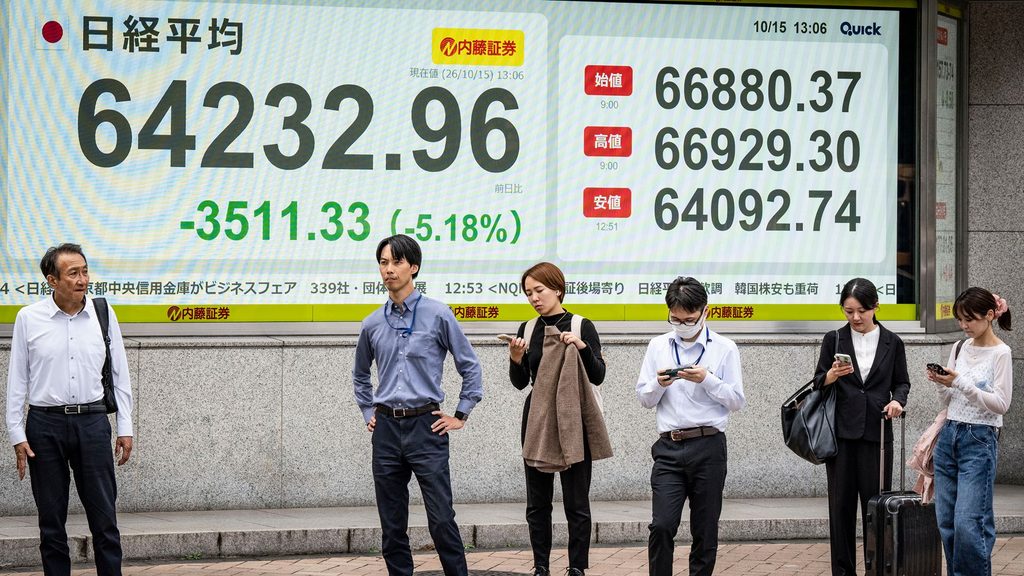
Global artificial intelligence stocks are suffering a sweeping sell-off, wiping approximately $1.6 trillion from the market value of U.S. semiconductor companies as growing concerns over the cost of the AI boom send shockwaves through international financial markets. According to Reuters, the Philadelphia Semiconductor Index lost roughly $1.64 trillion in market capitalization over six trading sessions, with losses threatening to approach $2 trillion as selling continued on October 15. The turmoil has spread across Asia, where South Korea's KOSPI plunged 7.57%, triggering a temporary trading halt, while Japan's Nikkei 225 dropped approximately 4.9%. Major semiconductor manufacturers, including Samsung Electronics and SK Hynix, suffered particularly sharp declines as investors reassessed the enormous spending commitments underpinning the technology industry. At the center of the growing financial anxiety is Nvidia-backed cloud computing company CoreWeave, whose bonds maturing in 2031 have surged beyond 16% in yield, a level commonly associated with distressed debt. Together, the collapsing stock valuations and soaring borrowing costs have intensified concerns that the massive investments fueling the AI expansion may be financially unsustainable.
CoreWeave has emerged as a particularly closely watched example of the financial pressures confronting the AI infrastructure industry, with its shares plunging more than 15% on October 14 before facing additional selling pressure the following morning. The company, which rents computing power built around Nvidia's high-performance chips to AI developers, has accumulated approximately $50 billion in debt according to figures cited by Reuters. Its business model depends heavily on borrowing money to purchase expensive processors, construct data centers and expand computing capacity before generating sufficient revenue to recover those investments. Investors have become increasingly concerned about whether the company can meet its financing obligations if borrowing costs continue rising or demand for AI computing capacity grows more slowly than anticipated. The warning signs have become especially visible in the bond market, where certain CoreWeave securities are trading at prices traditionally associated with financially distressed borrowers. Its unsecured bonds maturing in 2032 have fallen below 80 cents on the dollar, while the yield on a separate bond issue due in 2031 has exceeded 16%. Those figures do not establish that CoreWeave is facing bankruptcy, but they demonstrate how sharply investors have reassessed the financial risks associated with its debt-dependent expansion strategy.
«Yikes.»
-Elon Musk
The growing unease surrounding CoreWeave erupted into a broader debate over whether the AI industry's enormous infrastructure investments could be creating a financial bubble, drawing reactions from prominent Silicon Valley investors and Elon Musk. On October 13, venture capitalist Chamath Palihapitiya shared a chart on X showing that the yield on $1.25 billion of CoreWeave bonds maturing in 2032 had briefly reached 15% before closing at approximately 14.5%. Alongside the figures, he raised a pointed question: «Is the AI buildout creating a private credit bubble?» Musk responded with a single word: «Yikes.» Their exchange attracted widespread attention as other companies associated with AI infrastructure experienced significant stock market declines. Nebius, another provider of specialized computing services, fell approximately 10%, while Oracle also suffered substantial losses as investors scrutinized the financing required to sustain its data center expansion. The concern extends beyond one company's balance sheet, raising questions about how much of the industry's projected growth depends on continued access to affordable borrowing. Although no industry-wide bubble has been established, the pressure spreading from corporate bonds into global technology stocks has made the financial foundations of the AI boom a central concern for investors.
The financial pressure weighing on the AI industry has been compounded by a resurgence in U.S. inflation, raising the prospect that companies already borrowing heavily to expand their operations could face even higher financing costs. Figures released by the Bureau of Labor Statistics on October 15 showed that wholesale prices increased 1.3% in September, the largest monthly advance since March 2022, bringing annual producer price inflation to 6.3%, its highest level in nearly four years. The unexpected acceleration followed other troubling inflation indicators and reinforced expectations that the Federal Reserve could be forced to maintain elevated interest rates or tighten monetary policy further. For AI infrastructure developers, whose expansion plans often require substantial debt financing years before projects become fully profitable, the consequences could be significant. Higher borrowing costs make new data centers more expensive to construct and increase the financial burden on companies refinancing existing obligations. Even businesses experiencing strong customer demand could find themselves under pressure if interest expenses rise faster than revenue, creating an increasingly difficult environment for an industry whose growth has depended on access to enormous amounts of capital.
Those concerns received additional weight from a new warning issued by research firm Gartner on October 14, suggesting that the financial risks surrounding the AI expansion could extend into the trillions of dollars. The firm estimates that more than $3.5 trillion in AI infrastructure investments could be exposed to asset write-downs by 2030 if companies maintain their current spending trajectory. Gartner analyst Will Sommer explained that AI providers are expected to invest nearly $1 trillion in infrastructure during 2026 alone, followed by another $6 trillion between 2027 and 2030. However, he warned that projected customer spending would be «insufficient to support profitable returns on all planned AI capital expenditures during this period.» According to Gartner's calculations, data center operators would need to generate approximately $8.5 trillion in cumulative revenue through 2030 to cover investment costs, financing expenses and a 12% return on invested capital, while attributable AI revenue is projected to reach no more than $3.6 trillion. The firm also predicts that more than 80% of specialized AI cloud providers, known as neoclouds, could cease operating independently by 2030 because of financial pressures and industry consolidation. These estimates are forecasts rather than confirmed future losses, but they highlight the potential gap between the industry's investment commitments and the revenue needed to justify them.
«Is the AI buildout creating a private credit bubble?»
-Venture capitalist, Chamath Palihapitiya
Despite the mounting concerns, CoreWeave's leadership has pushed back against the increasingly negative market sentiment, arguing that the company's substantial customer commitments provide a stronger financial foundation than its falling securities suggest. In an internal memorandum obtained by Reuters, Chief Executive Mike Intrator told employees that financial markets can sometimes «misunderstand and act irrationally», while maintaining that CoreWeave's contracted business was more than sufficient to support its debt obligations. The company reported a revenue backlog of $104.2 billion in the second quarter and subsequently disclosed more than $25 billion in additional customer commitments during the third quarter. CoreWeave also benefits from a $6.3 billion agreement with Nvidia, under which the chipmaker is obligated to purchase certain computing capacity that CoreWeave cannot sell to other customers through April 2032, subject to contractual conditions. Meanwhile, co-founder Brannin McBee has outlined plans to pursue investment-grade financing and tap into additional sources of institutional capital, including insurance companies, to support future expansion. Nevertheless, long-term contracts do not eliminate refinancing risks, and substantial future revenues must still be converted into cash while infrastructure and interest expenses continue to accumulate. The wider question confronting the AI industry is no longer simply whether demand for advanced computing will continue growing, but whether the extraordinary borrowing and investment required to satisfy that demand can ultimately generate sustainable financial returns.
Created by humans, assisted by AI.
 FBI arrests OpenAI engineer after multiple secret recording devices found at company headquarters
 Netflix announces 1,000 layoffs while boasting its business is strong and growing
